Hum sab ka ek standard financial plan hota hai: Job lagti hai, salary aati hai, aur CA bolta hai ki tax bachane (Section 80D) ke liye health insurance le lo. Hum online jaate hain, apne budget ke hisaab se sabse sasta premium dekhte hain, 5 Lakh ka Sum Insured select karte hain, aur “Buy Now” par click kar dete hain.
Lekin Indian healthcare system ki asliyat kaafi alag hai: Health insurance hona, aur ek “sahi” health insurance hona, in dono baaton mein zameen-aasman ka farq hai.
India mein medical inflation lagbhag 14-15% ke rate se badh raha hai. Aaj se 5 saal pehle jo 5 Lakh ki policy kaafi lagti thi, aaj kisi achhe private hospital ke ICU ka ek hafte ka bill usse zyada aa jata hai. Sabse bada jhatka tab lagta hai jab medical emergency ke waqt pata chalta hai ki aapki policy mein ek aisi hidden clause thi jiski wajah se hospital bill ka 30% hissa aapko apni pocket se dena padega.
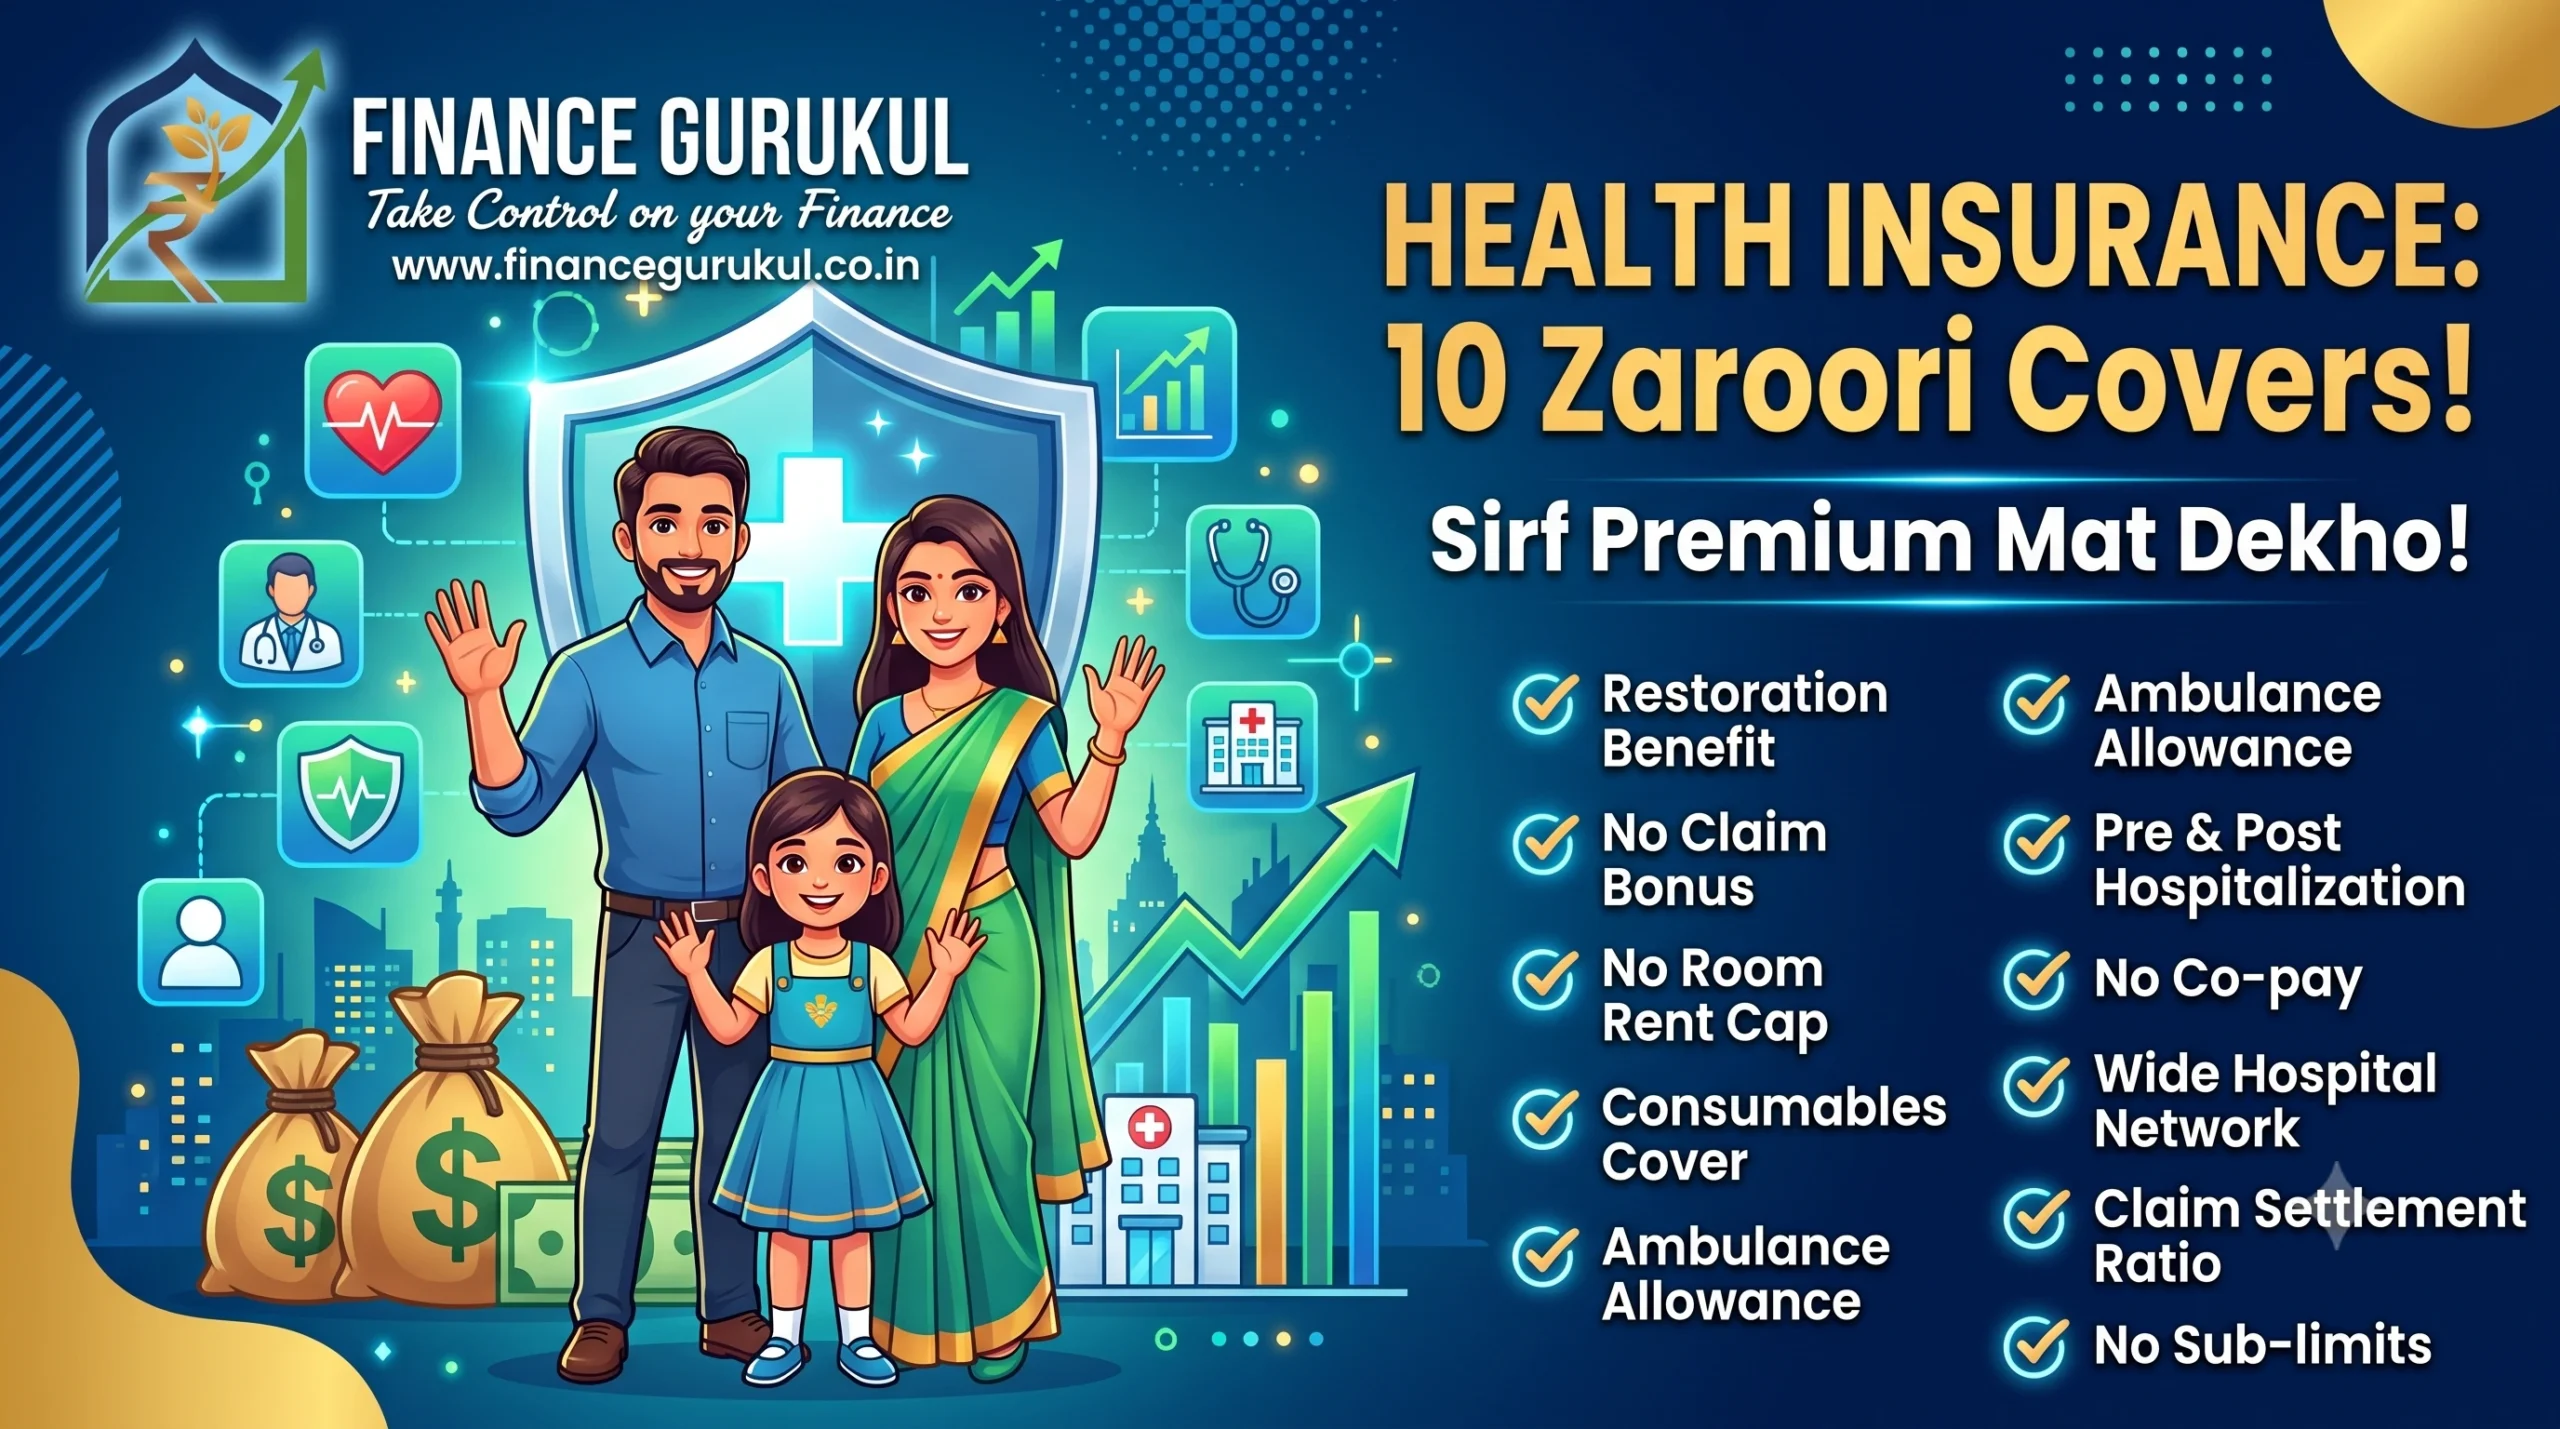
Finance Gurukul mein hamara manna hai ki fine print (chhoti lines) padhne ka kaam hamara hai, taaki aap secure rahein. Agar aap nayi policy lene ka soch rahe hain ya purani ko port karna chahte hain, toh sirf premium aur base cover mat dekhiye. Apni policy mein in 12 important features (pillars) ko zarur check karein jo ek normal policy ko ek “bulletproof” financial shield banate hain.
1. No Cap on Room Rent (Room Rent ki Limit) – The Silent Claim Killer
Agar aap is poore blog se sirf ek cheez seekhna chahte hain, toh wo ye hai: Kabhi bhi aisi policy mat lijiye jisme room rent par cap (limit) ho.
Bahut si entry-level policies mein hospital room rent par limit hoti hai, jo generally Sum Insured ka 1% per day (aur ICU ke liye 2%) hoti hai. Yaani agar aapki 5 Lakh ki policy hai, toh aapka room rent limit Rs. 5,000 per day hoga.
Nuksan kahan hota hai (The Trap):
Maan lijiye aap Lucknow ya kisi aur shahar ke top hospital mein admit hote hain aur wahan private room ka charge Rs. 8,000 per day hai. Aapko lagega ki aapko sirf extra Rs. 3,000 hi toh dene hain. Lekin hospitals mein doctor ki fees, nursing charges, aur operation theatre ka cost aapke room category se linked hota hai. Agar aapka room rent limit se 60% zyada hai, toh insurance company “Proportionate Deduction” lagati hai aur aapke poore medical bill se 60% kaat leti hai. Ek 2 Lakh ki surgery mein aapko achanak Rs. 80,000 apni pocket se dene pad sakte hain, sirf isliye kyunki aapne galat room choose kiya.
Finance Gurukul Advice: Hamesha wahi policy select karein jisme saaf likha ho “No Cap on Room Rent” ya “Any Room Category”.
2. Zero Co-Payment: Bill Share Karne Ki Zaroorat Nahi
Co-payment ek aisi clause hai jisme insurance company aapse kehti hai ki final claim amount ka ek fixed percentage aapko khud dena hoga. Agar aapki policy mein 20% co-pay hai aur hospital ka bill 10 Lakh aata hai, toh insurance company sirf 8 Lakh degi. Baaki ke 2 Lakh aapko apni savings se dene honge.
Insurance companies co-pay clause ka use karke annual premium ko sasta kar deti hain, taaki policy attractive lage. Ye mostly senior citizens ki policies mein ya Tier 2/Tier 3 cities (Zone-based co-pay) mein milta hai.
Finance Gurukul Advice: Apne ya apni family ke liye policy lete waqt 0% co-pay wali policy hi lein. Aaj thoda sa extra premium dena kal ke bade claim ke waqt aapki poori savings bacha lega.
Also Read: Understanding the Importance of Term Insurance
3. Restoration Benefit (The Magic Refill)
Sochiye aapke paas 10 Lakh ki family floater policy hai. March ke mahine mein kisi major surgery ki wajah se hospital ka bill 8 Lakh aata hai aur claim settle ho jata hai. Ab poore saal ke liye aapki policy mein sirf 2 Lakh bache hain. Agar 2 mahine baad family mein kisi aur ko dengue ho jaye ya emergency operation ki zarurat pade, toh kya hoga?
Yahan kaam aata hai Restoration Benefit (jise Refill ya Recharge bhi kehte hain). Jaise hi aapka base sum insured khatam hota hai, company aapke cover ko dobara 100% restore (refill) kar deti hai.
Kya check karein:
- Unrelated vs. Same Illness: Purani policies mein restoration sirf kisi nayi (unrelated) beemari par milta tha. Aaj ki modern policies mein “same illness” par bhi restoration milta hai.
- Trigger Point: Check karein ki restoration base cover ke partial exhaustion (thoda khatam hone) par trigger hota hai ya poora 100% khatam hone par. Hamesha partial exhaustion wala option better hota hai.
4. Consumables Cover: PPE Kits Aur Gloves Ka Kharcha
Agar aapne kabhi hospital ka final bill dhyan se dekha ho, toh usme “Non-Medical Expenses” ya “Consumables” ki ek lambi list hoti hai. Isme gloves, masks, PPE kits, syringes, cotton, admission kits aur aisi bahut si cheezein shamil hoti hain.
COVID ke time par logo ko realize hua ki ye chhote-chhote items total bill ka 10% se 20% hissa ban jate hain. Yaani 5 Lakh ke bill mein 70,000 se 80,000 rupaye sirf consumables ke ho sakte hain jo insurance company standard policy mein pay nahi karti.
Finance Gurukul Advice: Apni policy mein “Consumables Cover” (jo kabhi-kabhi ‘Active Care’ ya ‘Safeguard’ add-on rider ke naam se milta hai) zaroor add karein. Isse aapko ek sacha zero-deduction cashless experience milega.
5. No Sub-Limits on Specific Diseases
Insurance isliye liya jata hai taaki unpredictable bade kharche cover ho sakein. Lekin kuch insurers common surgeris par apni taraf se limit laga dete hain.
Jaise ki agar aapka total cover 10 Lakh hai, toh bhi fine print mein likha hoga:
- Cataract (Motiyabind) surgery: Sirf Rs. 30,000 per eye.
- Knee replacement: Limit Rs. 1.5 Lakhs.
- Modern treatments (Robotic Surgery aadi): Sum Insured ka sirf 50%.
Finance Gurukul Advice: Policy document ko carefully padhein. Market ki best policies mein specific diseases par koi sub-limit nahi hoti, aur aap poora base sum insured in treatments ke liye use kar sakte hain.
6. Cumulative Bonus (No Claim Bonus)
Health insurance sirf claim lene ke liye nahi hota, ye aapko fit rehne par reward bhi karta hai. Cumulative Bonus ya No Claim Bonus (NCB) ka matlab hai ki har us saal jisme aapne koi claim nahi liya, aapka base cover badha diya jata hai, wo bhi bina premium badhaye.
Standard policies har claim-free saal par 10% ya 20% cover badhati hain. Lekin aaj kal aisi bohot si advanced plans hain jo ek hi claim-free saal mein aapka Sum Insured 50% ya 100% tak badha deti hain.
Pro Tip: Agar aap 10 Lakh ki aisi policy lete hain jisme 100% NCB hai, toh bina koi claim liye agle hi saal aapka cover automatically 20 Lakh ka ho jayega. Medical inflation ko beat karne ka ye sabse smart tareeqa hai.
💡 Confused About Choosing the Best Health Insurance Plan?
Market mein 100 se zyada health policies hain, aur har company claim karti hai ki unki policy best hai. Galat policy lene se behtar hai ki aap kisi expert ki guidance lein.
Finance Gurukul aapki age, family size, aur budget ke hisaab se sabse Best Health Insurance Plan select karne mein aapki help karta hai. Sirf policy bechna nahi, balki fine print (hidden clauses) samjhana aur emergency claims ke waqt aapka pura sath dena hamari guarantee hai.
7. Comprehensive Pre and Post-Hospitalization Cover
Medical kharche sirf hospital mein admit hone par shuru nahi hote, aur discharge hone par khatam nahi hote.
- Pre-hospitalization: Admit hone se pehle ke doctor consultations, blood tests, MRI, aur scans.
- Post-hospitalization: Discharge hone ke baad ki dawaiyan, physiotherapy, aur follow-up check-ups.
Ek achhi policy kam se kam 60 days of pre-hospitalization aur 90 se 180 days of post-hospitalization cover karti hai. Discharge ke baad apne saare pharmacy bills aur test receipts sambhal kar rakhein, aap inhe insurance company se reimburse karwa sakte hain.
8. All Day-Care Procedures Covered
Medical technology ab bahut advance ho chuki hai. Jo surgeries pehle ek hafte ka hospital stay maangti thi (jaise cataract, kidney stone removal, dialysis, ya chemotherapy), wo ab kuch hi ghanton mein ho jati hain.
Kyunki inme patient 24 ghante ke liye admit nahi hota, isliye purane rules ke hisaab se claims reject ho jate the. Ab insurance companies ek list banati hain jise “Day Care Procedures” kaha jata hai.
Finance Gurukul Advice: Aisi policy mat lijiye jo ginti ke “140 or 150 day-care procedures” cover karti ho. Wahi policy best hai jisme saaf likha ho: “All day-care procedures are covered up to the Sum Insured.”
9. Ambulance Allowance (Including Air Ambulance)
Medical emergency mein private ambulances ke sath rate negotiate karne ka time nahi hota. Zyada tar policies road ambulance cover toh karti hain, par uski limit 1000 se 2000 rupaye tak fix kar deti hain. Bade sheharo mein fully equipped ICU ambulance ka charge isse kahin zyada hota hai.
Aapko aisi policy dekhni chahiye jisme:
- Road Ambulance: Actual cost tak covered ho ya limit kafi high ho (Rs. 5,000 – Rs. 10,000).
- Air Ambulance: Agar aap aise area mein rehte hain jahan bade hospitals door hain, toh Air Ambulance cover (jo 2.5 Lakh se 5 Lakh tak hota hai) sach mein kisi ki jaan bacha sakta hai.
10. Domiciliary Hospitalization (Home Care)
COVID-19 ne humein sikhaya ki aisi situations bhi aa sakti hain jahan hospitals mein bed hi available na ho. Aise mein doctors ghar par hi ICU jaisa setup (nursing staff, oxygen cylinder, IV drip) lagane ki advice dete hain.
Ise Domiciliary Hospitalization kehte hain. Make sure ki aapki policy is kharche ko poore Sum Insured tak cover karti ho. Iski aam shart ye hoti hai ki treatment lagatar 3 din se zyada chalna chahiye aur doctor ka written approval hona chahiye ki hospital mein bed nahi mila ya patient ko move karna possible nahi hai.
2 Bonus Tips
11. Strong Cashless Hospital Network
Kitne bhi achhe features kyun na ho, agar emergency ke waqt aapko cash arrange karke payment karni pade aur fir reimbursement ke liye mahino wait karna pade, toh insurance ka fayda nahi.
Koi bhi policy final karne se pehle, unka network hospital list zarur check karein.
- Kya aapke shehar (aur aapke ghar ke sabse paas) ke top hospitals unke cashless panel par hain?
- Kya wo company Third-Party Administrator (TPA) use karti hai ya unki apni In-house Claim Settlement team hai? In-house teams wale insurers cashless approval kafi jaldi (often 30 se 60 minute mein) process kar dete hain as compared to external TPAs.
12. Claim Settlement Ratio (CSR) aur Incurred Claim Ratio (ICR)
Last par sabse important—insurance company ka khud ka report card kaisa hai?
- Claim Settlement Ratio (CSR): Ye batata hai ki company ke paas aaye total claims mein se unhone kitne pass kiye. Hamesha 90% ya usse zyada CSR wali company choose karein. Lekin dhyan rahe, sirf CSR dekhna kaafi nahi hai kyunki kai baar companies chhote claims pass karke bade claims reject kar deti hain apna ratio theek rakhne ke liye.
- Incurred Claim Ratio (ICR): Ye company ki asal financial health batata hai. Ye dikhata hai ki company ne premium ke roop mein jitna paisa kamaya, usme se kitna paisa claims pay karne mein kharch kiya. 65% se 85% ka ICR sabse best mana jata hai. Agar ye 50% se kam hai, toh matlab company bohot claims reject kar rahi hai profits banane ke liye. Agar ye 100% se zyada hai, toh matlab company loss mein ja rahi hai aur agle saal pakka aapka premium bohot zyada badha degi.
The Final Verdict: Peace of Mind Buy Karein
Health insurance koi tax-saving scheme nahi hai, ye aapki zindagi bhar ki kamayi ko protect karne ka sabse bada tool hai. Ek badi medical emergency aapke saalo ke mutual fund SIPs, fixed deposits, aur stock market gains ko ek jhatke mein khatam kar sakti hai.
Jab bhi aap top companies ki policies compare karein, toh is checklist ko samne rakhein. Room Rent limit, Co-pays, aur Consumables par kabhi compromise mat karein. Hamara end goal ye hona chahiye ki jab aap ya aapka koi apna hospital se discharge ho, toh poora focus sirf recovery par ho, billing counter par credit card swipe karne par nahi.
Kya aap abhi bhi apne aur apni family ke liye sahi cover choose karne mein uljhe hue hain? Niche comment karke apne questions puchiye ya direct [Finance Gurukul Team Se Contact Karein]. Hum aapka financial foundation strong banane ke liye hamesha ready hain!


